Upcoming Webinars:
Tuesday, October 20, 2026
Register to attend 1, 2, or all 3 Free Webinars below.
If you are married, both spouses are encouraged to attend.
45 Years of Acquired Wisdom in One Day:
A War Weary CPA/Attorney/Financial Advisor Reveals All
Our goal for this webinar series:
Distill the most valuable retirement and estate-planning lessons from Jim Lange’s 45-year career into one day. Jim will also draw on his 10 best-selling books, 37 Wall Street Journal citations, and five years hosting a radio show featuring guests such as John Bogle and Bill Bengen.
Session One: 10:00 AM – Noon (Eastern)
Costly Retirement & Estate Planning Mistakes and Missed Opportunities
Over 45 years, Jim has seen the same costly retirement and estate-planning mistakes and missed opportunities recur repeatedly. Some accelerate income taxes, send the wrong assets to the incorrect beneficiaries, or undermine the financial security of a surviving spouse. Others cause families to miss opportunities to spend or give more during their lifetimes, reduce taxes, or improve the after-tax result for their heirs. In this session, he’ll focus on a selection of the most consequential mistakes and missed opportunities he has encountered and explain strategies that can help families avoid them.
Some of the issues Jim will cover include:
-
Dying rich is a bad plan. Most of our clients could afford to spend more and make larger gifts during their lifetimes. Part of it is financial conservatism; some of it is simply not knowing how much they can safely spend or gift. So, the unspoken plan becomes: accumulate a lot, spend and gift far less than you can afford, and leave the rest to your children when you die. But your kids could likely use the money now, not when you die. Waiting can also dramatically increase the taxes they ultimately pay, because inherited IRA distributions may be stacked on top of peak-career income and taxed at relatively high rates.
Jim will cover Bill Bengen’s updated safe-withdrawal-rate analysis and explain how it can provide an objective framework for estimating your own sustainable retirement spending. For many clients, that can mean enjoying more of their wealth, helping children when the money may be more useful, and still maintaining a strong margin of financial security throughout their own lifetimes.
- Underestimating the importance and complexity of Roth IRA conversions. This mistake is important enough that Session Two will be devoted to the Roth conversion opportunities Jim believes many families and advisors overlook.
- Not paying sufficient attention to the beneficiary designation of IRAs and retirement plans. Estate-planning attorneys are as guilty as clients in this area. Jim will explain why beneficiary designations can override the estate plan you thought you had, how IRA owners commonly get them wrong, and how estate-planning attorneys can cause a trust named as an IRA or retirement plan beneficiary to lose favorable tax treatment by failing to satisfy four critical conditions.
- Claiming Social Security too early. In one example, claiming at age 62 instead of 70 means a monthly benefit of $2,566 rather than $5,262 for the higher earner. For a married couple, that difference can amount to $300,000 or more over their joint lifetimes.
- Failing to build qualified disclaimers into your estate plan, unnecessarily limiting your family’s options after the first death and potentially leaving all your beneficiaries with less after taxes.
- Not considering our Who Gets What strategies that can save families hundreds of thousands of dollars in taxes.
- Not doing the math―especially regarding Roth conversions.
Session Two: 12:30 PM to 2:00 PM (Eastern)
Roth IRA Conversions:
Peer-Reviewed Concepts Most CPAs and Financial Advisors Overlook
The difference between an optimized Roth conversion strategy and either doing nothing or relying on a “rule of thumb” such as converting up to the top of a particular tax bracket can be enormous. Depending on the family’s circumstances, the projected after-tax savings can reach hundreds of thousands of dollars and, in some cases, more than $1 million.
- Proactive Multi-Year Tax Planning: Why the best answer is often not simply whether to convert, but how much to convert in each year.
- Coordinating Roth Conversions with the Rest of Your Retirement Plan: How conversion timing can affect tax brackets and Medicare premiums, and why Social Security claiming decisions should be considered alongside Roth conversions.
- Advanced Roth Opportunities: When after-tax retirement-plan dollars and other less familiar strategies may offer additional planning opportunities.
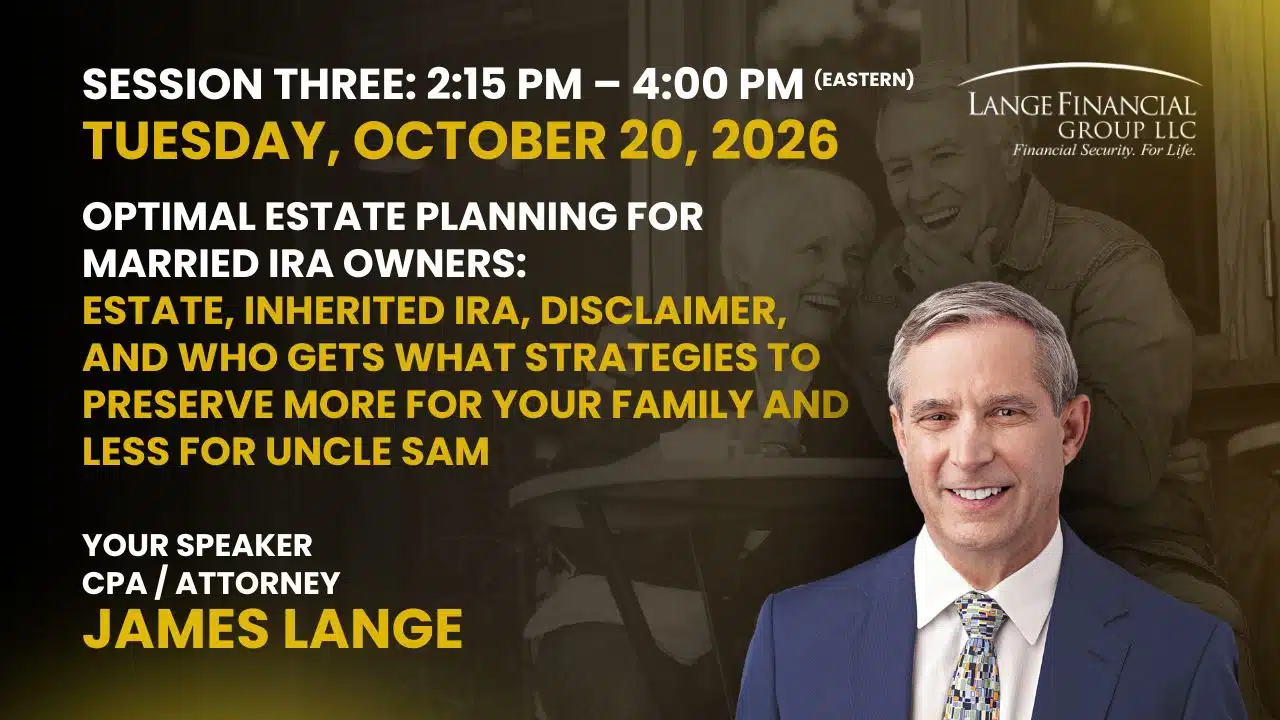
Session Three: 2:15 PM – 4:00 PM (Eastern)
Optimal Estate Planning for Married IRA Owners:
Estate, Inherited IRA, Disclaimer, and Who Gets What Strategies to Preserve More for Your Family and Less for Uncle Sam
If you are anything like most of our clients, the biggest problem with your estate plan is not its exposure to estate or transfer taxes, but the income tax burden it could create for your heirs. Dying with a large traditional IRA can trigger a substantial income-tax burden for your heirs, much of which could have been prevented with proper planning. Roth conversions are part of the solution, but beneficiary designations, trusts, disclaimers, and decisions about which assets go to which beneficiaries can be just as important. Jim will explain how these pieces can be coordinated to develop the ideal estate plan for most married IRA owners.
- Beneficiary Designations vs. Your Will or Trust: Why the beneficiary designations attached to retirement accounts can determine who receives those assets, regardless of what your will may say.
- Trust Planning for Retirement Accounts: When direct inheritance may make sense and when the protection offered by a trust may justify additional complexity.
- Lange's Cascading Beneficiary Plan and Qualified Disclaimers: ℠ Jim will explain the cascading beneficiary plan he has favored since 1995, which has been used in over 3,000 estate plans, and show how its built-in flexibility has worked in real-life situations.
- Who Gets What? How thoughtful asset selection can maximize the after-tax value of your estate by matching different assets to the beneficiaries who can receive them most tax-efficiently. For example, an inherited IRA worth $100,000 may leave your heirs only $76,000 after income taxes. Leave that same IRA to charity and direct $100,000 of after-tax assets to the heir instead, and both the charity and the heir can receive the full $100,000.
- Lifetime Gifts vs. Inheritances: When helping children or grandchildren during your lifetime may produce a better family result than simply continuing to accumulate assets until death.
In thousands of consultations over 45 years, Jim has never had a client say the meeting wasn’t worth their time. This webinar is your opportunity to benefit from that same depth of knowledge—in a single day. Register now to reserve your place and receive the complimentary digital bonus materials described below.
About Your Presenter: James Lange, CPA/Attorney
Jim Lange’s tax and estate planning strategies have been endorsed by The Wall Street Journal (37 times). He has authored 10 best-selling financial books. Jim authored the first peer-reviewed article on Roth IRAs in 1998 which was published in AICPA’s journal, The Tax Adviser. He has authored five peer-reviewed articles in Trusts & Estates, and he is a regular contributor for Forbes.com.
Some of Jim’s books have become classics endorsed by the country’s top experts. Retire Secure! was endorsed by Charles Schwab, Larry King, Jane Bryant Quinn, and 50 other experts; The Roth Revolution, endorsed by Ed Slott and Robert S. Keebler; The $214,000 Mistake, How to Double Your Social Security and Maximize Your IRAs, endorsed by Larry Kotlikoff, Jonathan Clements, and Paul Merriman; The Retirement Plan Owner’s Guide to Beating the New Death Tax, endorsed by Burton Malkiel and Larry Swedroe; Retire Secure for Professors and TIAA Participants, endorsed by Roger Ibbotson and Stephan R. Leimberg, Esq.; and Retire Secure for Parents of a Child with a Disability endorsed by Tatyana McFadden and James M. Dahle, MD.
Attend Jim Lange’s Webinars for FREE - Reserve Your Seats Today!
Tuesday, October 20, 2026
Register for one all three sessions now!
Valuable Digital Bonus Materials:
Yours FREE When You Register!
Register today and you’ll receive digital copies of all the following resources:
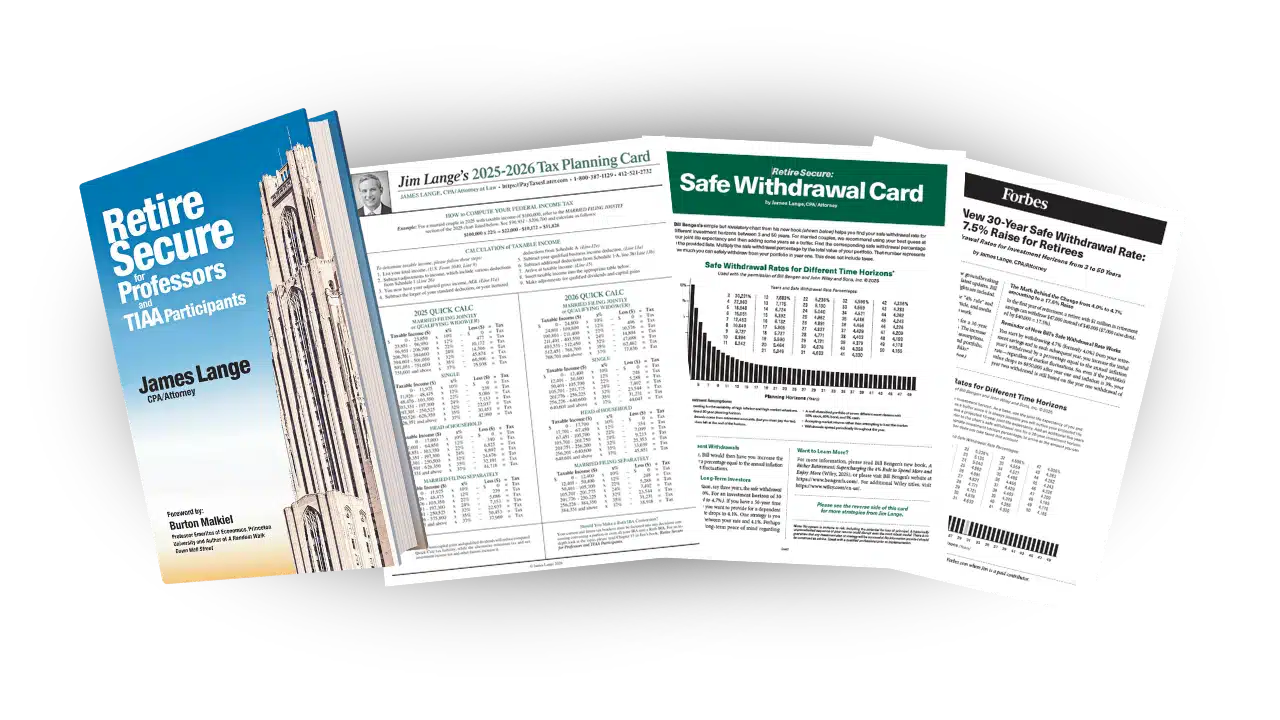
- Retire Secure for Professors and TIAA Participants: Jim’s 472-page book, that enjoys 78 glowing reviews on Amazon.com. Note: 90% of the content of this book pertains to all IRA and retirement plan owners.
- Retire Secure Safe Withdrawal Kit: Jim’s com article, “Bill Bengen’s New 30-Year Safe Withdrawal Rate: A 17.5% Raise for Retirees,” plus the Retire Secure Safe Withdrawal Card. Learn why Bill’s updated research raises the traditional 30-year safe withdrawal rate from 4% to 4.7%, and use the accompanying planning card to estimate sustainable first-year withdrawals for investment horizons ranging from 3 to 50 years.
- Lange Financial Group’s 2025–2026 Tax Planning Card: A practical quick-reference guide to 2025 and 2026 federal tax brackets, standard and senior deductions, retirement-plan contribution limits, Pennsylvania taxes, estate and gift-tax figures, and other tax-planning information.
Disclaimer: Lange Accounting Group, LLC offers guidance on retirement plan distribution strategies, tax reduction, Roth IRA conversions, saving and spending strategies, optimized Social Security strategies, and gifting plans. Although we bring our knowledge and expertise in estate planning to our recommendations, all recommendations are offered in our capacity as CPAs. We will, however, potentially make recommendations that clients could have a licensed estate attorney implement.
Asset location, asset allocation, and low-cost enhanced index funds are provided by the investment firms with whom Lange Financial Group, LLC is affiliated. This would be offered in our role as an investment advisor representative and not as an attorney.
Lange Financial Group, LLC, is a registered investment advisory firm registered with the Commonwealth of Pennsylvania Department of Banking, Harrisburg, PA. In addition, the firm is registered as a registered investment advisory firm in the states of AZ, FL, NY, OH, and VA. Lange Financial Group, LLC may not provide investment advisory services to any residents of states in which the firm does not maintain an investment advisory registration. Past performance is no guarantee of future results. All investing involves risk, including the potential for loss of principal. There is no guarantee that any strategy will be successful. Indexes are not available for direct investment. If you qualify for a free consultation with Jim and attend a meeting, there are two services he and his firms have the potential to offer you. Lange Accounting Group, LLC could offer a one-time fee-for-service Financial Masterplan. Under the auspices of Lange Financial Group, LLC, you could potentially enter into an assets-under-management arrangement with one of Lange’s joint venture partners.
Please note that if you engage Lange Accounting Group, LLC and/or Lange Financial Group, LLC for either our Financial Masterplan service or our assets-under-management arrangement, there is no attorney/client relationship in this advisory context.
Although Jim will bring his knowledge and expertise in estate planning to this workshop and to the meetings, it will be conducted in his capacity as a financial planning professional and not as an attorney. This is not a solicitation for legal services.